Business Loans
How to Get a Business Loan in Gwalior: Eligibility, Documents & Best Options
Looking for a business loan in Gwalior? Explore loan options, eligibility, documents, interest rates and practical tips to secure business funding.
Introduction
Whether you are planning to start a new business, expand an existing manufacturing unit, purchase machinery or manage day-to-day operational expenses, access to the right financing can make a significant difference.
Gwalior has business opportunities across manufacturing, trading, retail, healthcare, education, hospitality, transportation and other service sectors. However, business growth often requires additional capital at the right time.
A business loan in Gwalior can help entrepreneurs arrange funds for expansion, working capital, equipment purchases, infrastructure development and other business requirements.
Banks, Non-Banking Financial Companies (NBFCs) and eligible financial institutions offer different financing solutions depending on the business profile, financial performance, repayment capacity and funding requirements.
Understanding the available loan options, eligibility criteria and documentation before applying can help you make a more informed financial decision.
Key Takeaways
- Business loans are available for eligible new and existing businesses in Gwalior.
- Banks and NBFCs offer secured and unsecured business financing.
- Loan eligibility depends on turnover, profitability, credit history and repayment capacity.
- Udyam Registration can support eligible MSMEs in accessing formal business credit.
- Working capital loans and term loans serve different financial requirements.
- A properly prepared business plan and financial documents can improve your application.
- Loan approval, interest rates and funding amounts depend on the lender's assessment.
What Is a Business Loan?
A business loan is a financial facility provided by a bank, NBFC or other eligible lending institution to support business-related financial requirements.
Unlike personal loans, business loans are generally assessed based on the financial position, operational performance and repayment potential of the business.
Businesses in Gwalior can use business financing for several purposes, including:
- Starting a new business.
- Expanding an existing business.
- Purchasing machinery and equipment.
- Buying commercial property or developing infrastructure.
- Managing inventory and operational expenses.
- Increasing production capacity.
- Opening additional branches or business locations.
- Managing cash flow gaps.
Example: How Business Financing Can Help
Suppose a manufacturing business in Gwalior wants to increase its production capacity by purchasing new machinery.
The business may require additional capital for machinery, installation, raw materials and employee expenses.
Instead of using all its existing working capital, the business owner can explore a suitable term loan or equipment financing facility.
The right financing structure can help the business manage expansion expenses while maintaining sufficient funds for regular operations.
Types of Business Loans Available in Gwalior
Different businesses have different financial requirements. Selecting the right loan type is important because the repayment structure, security requirements and loan tenure can vary.
1. Unsecured Business Loan
An unsecured business loan is generally offered without requiring property or other traditional collateral.
Suitable for:
- Established small businesses.
- Traders and distributors.
- Service providers.
- Businesses requiring short- or medium-term capital.
Lenders may evaluate turnover, banking transactions, profitability, credit history and business stability.
2. Secured Business Loan
A secured business loan is backed by acceptable collateral, such as commercial or residential property, depending on the lender's policy.
Suitable for:
- Businesses requiring substantial funding.
- Established manufacturing units.
- Infrastructure development.
- Business expansion and long-term investments.
The loan amount depends on property valuation, ownership documents, repayment capacity and lender policies.
3. Working Capital Loan
Working capital financing helps businesses manage their regular operational expenses.
It can be used for:
- Purchasing raw materials.
- Maintaining inventory.
- Paying suppliers.
- Managing receivables.
- Meeting seasonal business requirements.
Common facilities include cash credit and overdraft arrangements.
4. Machinery and Equipment Loan
Businesses planning to purchase or upgrade machinery can explore equipment financing.
It is particularly relevant for manufacturing units, engineering businesses, packaging companies and production facilities.
5. MSME Business Loan
Micro, Small and Medium Enterprises can explore specialised financing options offered by banks and eligible financial institutions.
Eligible micro and small enterprises may also explore credit facilities supported by the Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE).
Business Loan Comparison Table
Loan TypeMain PurposeSecurityUnsecured Business LoanBusiness operations and expansionGenerally no traditional collateralSecured Business LoanLarge funding requirementsProperty or acceptable collateralWorking Capital LoanDaily operational expensesDepends on facility and lenderMachinery LoanEquipment purchasesFinanced equipment or other security, depending on lenderMSME LoanBusiness development and operationsDepends on scheme and lender
Business Loan Eligibility Criteria in Gwalior
Eligibility requirements differ between banks and NBFCs. However, most lenders evaluate the following factors before approving a business loan.
1. Business Vintage
Lenders generally prefer businesses with an established operating history. The required business vintage varies depending on the loan product.
New businesses may need a detailed project report, promoter contribution and a viable business plan.
2. Annual Business Turnover
Annual turnover helps lenders understand the scale of business operations.
Higher turnover does not automatically guarantee a higher loan amount. Lenders also consider profitability, existing liabilities and cash flow.
3. Credit Score and Repayment History
A healthy credit profile can strengthen a loan application.
Lenders may review:
- CIBIL or other credit bureau reports.
- Previous loan repayment records.
- Existing EMI obligations.
- Credit card payment history.
- Outstanding financial liabilities.
4. Profitability and Cash Flow
A business should demonstrate sufficient cash flow to manage existing obligations and repay the proposed loan.
Lenders may examine profit and loss statements, balance sheets and bank transactions.
5. Business Registration
Depending on the business structure and loan product, applicants may need:
- GST registration, where applicable.
- Udyam Registration, where applicable.
- PAN and business identity documents.
- Partnership or company registration documents.
- Relevant trade and operating licences.
6. Repayment Capacity
The lender assesses whether the business can comfortably repay the proposed loan without creating excessive financial pressure.
Documents Required for a Business Loan
Preparing the necessary documents before applying can make the loan application process smoother.
Personal Documents
- PAN Card.
- Aadhaar Card or other accepted identity proof.
- Address proof.
- Passport-size photographs.
- Promoter or director details.
Business Documents
- Business registration certificate.
- Udyam Registration Certificate, if applicable.
- GST registration and returns, where applicable.
- Partnership deed or company incorporation documents.
- Business address proof.
- Trade licences and relevant approvals.
Financial Documents
- Last 2–3 years' Income Tax Returns, where available.
- Audited financial statements, where applicable.
- Profit and loss statements.
- Balance sheets.
- Last 6–12 months' bank statements.
- Existing loan details.
- GST returns, where applicable.
Additional Documents for Secured Loans
- Property ownership documents.
- Property chain documents, where required.
- Approved building plan, where applicable.
- Property valuation and legal verification documents.
- Existing mortgage details, if any.
Important: The exact document list depends on the loan amount, business constitution, lender policy and type of financing.
How to Apply for a Business Loan in Gwalior: Step-by-Step Process
If you are planning to apply for business financing, follow these practical steps.
Step 1: Identify Your Funding Requirement
Determine how much funding your business actually needs.
For example:
- Machinery purchase: ₹25 lakh.
- Working capital: ₹15 lakh.
- Business expansion: ₹50 lakh.
Prepare a clear breakdown of the proposed expenses.
Step 2: Select the Right Loan Product
Choose between secured financing, unsecured business loans, working capital facilities and equipment loans.
The best option depends on your financial requirements and repayment capacity.
Step 3: Prepare Your Financial Documents
Organise your bank statements, financial statements, GST returns, ITRs and business registration documents.
Ensure that the information is accurate and consistent.
Step 4: Compare Banks and NBFCs
Explore financing options from different lenders.
Compare:
- Interest rates.
- Processing fees.
- Loan tenure.
- Collateral requirements.
- Repayment terms.
- Prepayment and foreclosure charges.
Step 5: Submit Your Application
Submit the completed application with the required documents through the lender's official website or authorised branch.
Step 6: Credit Assessment and Verification
The lender may verify your business operations, financial statements, credit history, property documents and repayment capacity.
Step 7: Loan Sanction and Disbursement
If your application meets the lender's requirements, the lender may issue a sanction letter specifying the approved amount, interest rate, tenure and other conditions.
Review the terms carefully before accepting the facility.
Government Schemes and Business Loan Support for Gwalior Entrepreneurs
Eligible businesses in Gwalior can explore various government-supported credit programmes.
1. CGTMSE Scheme
The Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) supports eligible collateral-free lending to micro and small enterprises through participating lending institutions.
Under the revised scheme effective from April 1, 2025, eligible credit facilities can receive guarantee support up to ₹10 crore, subject to scheme conditions and lender approval.
Important points:
- It is a credit guarantee mechanism, not a direct loan.
- Businesses apply through participating lenders.
- Udyam Registration is mandatory for new guarantee applications.
- Loan approval remains subject to credit appraisal.
- It does not mean every business automatically qualifies for collateral-free funding.
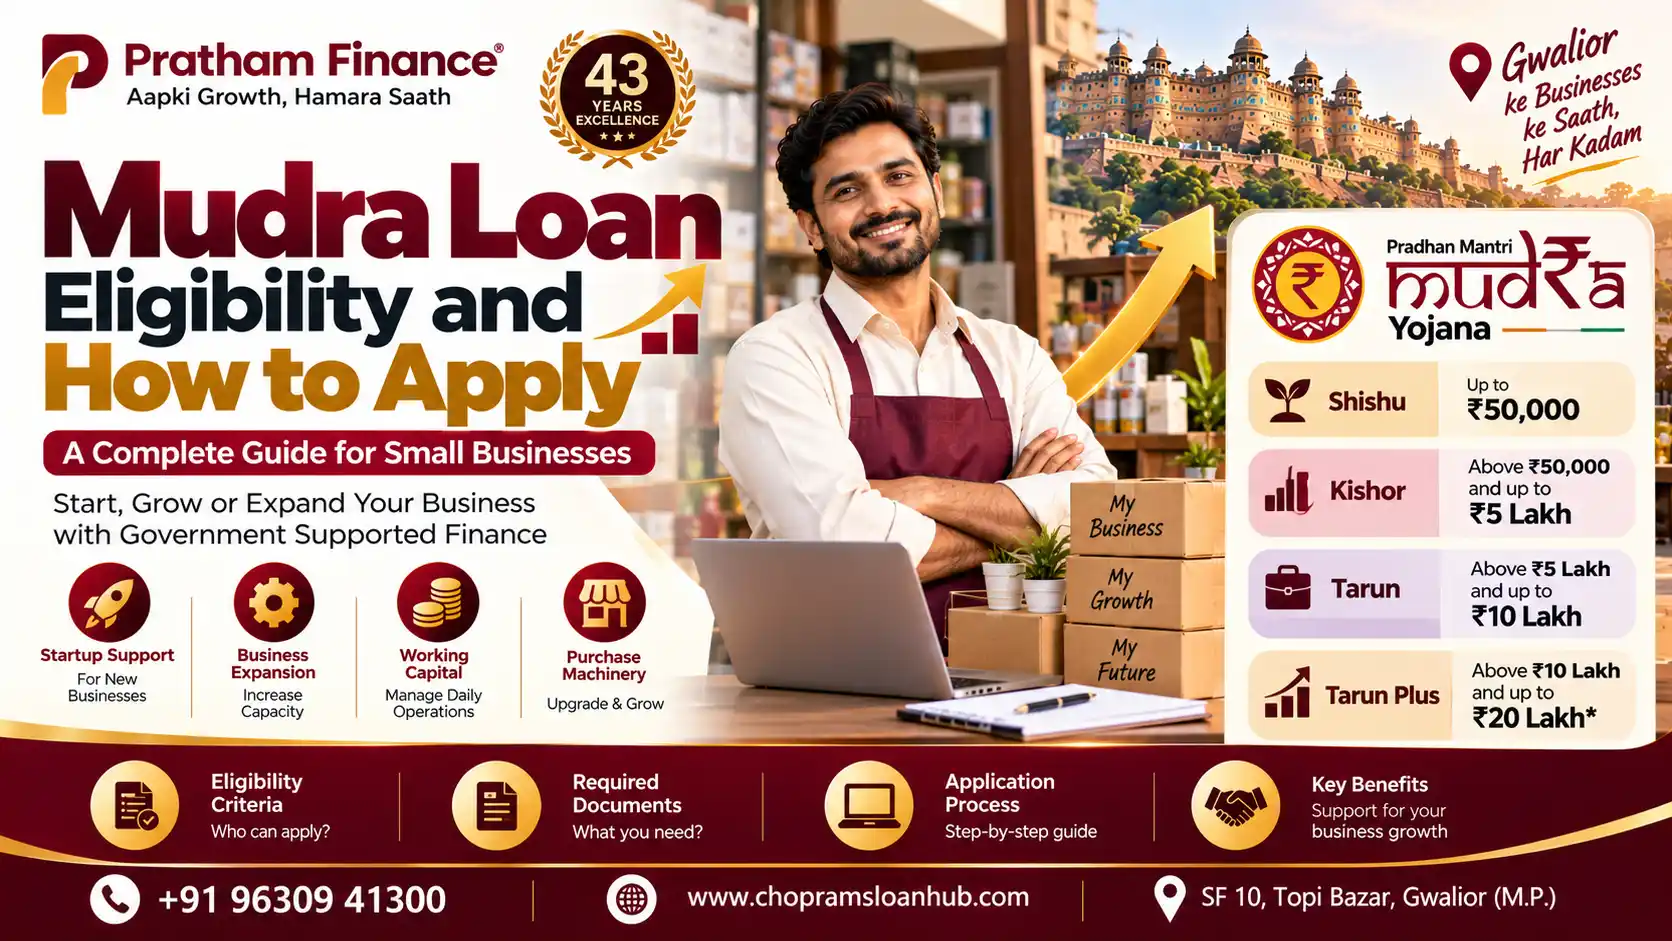
2. Pradhan Mantri MUDRA Yojana (PMMY)
MUDRA financing supports eligible micro enterprises engaged in manufacturing, trading and service activities.
The scheme has different funding categories, including Shishu, Kishor, Tarun and Tarun Plus.
Eligibility, loan limits and conditions depend on the applicable category and lender.
3. Prime Minister's Employment Generation Programme (PMEGP)
PMEGP is a government-supported credit-linked subsidy programme for eligible new micro-enterprise projects.
It can be considered by entrepreneurs planning to establish a new manufacturing or service enterprise, subject to the scheme's conditions.
4. Madhya Pradesh Entrepreneurship Support
Entrepreneurs can also explore applicable state government programmes through the District Trade and Industry Centre (DTIC), Gwalior.
Scheme availability, eligibility and benefits should be verified with the concerned department before applying.
How to Improve Your Business Loan Approval Chances
Getting a business loan is not only about submitting an application. Your financial preparation and business profile also matter.
Here are some practical ways to strengthen your application.
1. Maintain a Healthy Credit Profile
Pay existing EMIs and credit card dues on time. Avoid unnecessary loan applications.
2. Maintain Proper Financial Records
Keep your bank transactions, ITRs, GST returns and accounting records organised.
3. Show Consistent Business Cash Flow
Regular business transactions and healthy collections can help lenders assess repayment capacity.
4. Prepare a Detailed Project Report
For expansion or new business projects, prepare a report covering:
- Business overview.
- Project cost.
- Funding requirement.
- Expected revenue.
- Operating expenses.
- Projected cash flow.
- Repayment plan.
5. Reduce Existing Debt Where Possible
High existing liabilities can affect your repayment capacity. Review your outstanding obligations before applying.
6. Choose the Right Loan Amount
Apply for an amount supported by your actual business requirement and financial position.
7. Compare Multiple Financing Options
Do not select a loan based only on the advertised interest rate. Consider the complete borrowing cost and repayment conditions.
Where Can You Explore Business Loans in Gwalior?
Business owners can approach:
- Public sector banks.
- Private sector banks.
- Small Finance Banks.
- NBFCs.
- Eligible financial institutions.
- Government-supported MSME financing channels.
You can also approach the District Trade and Industry Centre, Gwalior, for information about applicable entrepreneurship and MSME support programmes.
Before finalising a lender, verify its regulatory status, official application channel, charges and loan agreement.
Frequently Asked Questions (FAQs)
1. How can I get a business loan in Gwalior?
You can apply through banks, NBFCs and eligible financial institutions. Prepare your business registration documents, financial statements, bank statements and identity proofs. The lender will evaluate your eligibility, credit history and repayment capacity.
2. What is the minimum credit score required for a business loan?
There is no single universal credit score requirement for every business loan. Banks and NBFCs follow their own credit policies. A stronger credit profile and consistent repayment history can improve your chances of approval.
3. Can I get a business loan without collateral in Gwalior?
Yes, eligible businesses may obtain unsecured business loans or collateral-free credit facilities. Eligible micro and small enterprises can also explore CGTMSE-backed financing through participating lenders. Approval depends on the lender's assessment and applicable scheme conditions.
4. Can a new business get a business loan?
Yes, new businesses can explore eligible startup and government-supported financing options. However, lenders may require a detailed project report, promoter contribution, business plan and evidence of project viability.
5. Which documents are required for an MSME loan?
Common documents include PAN, Aadhaar or accepted KYC documents, Udyam Registration, GST records where applicable, bank statements, ITRs, financial statements and business registration documents. Additional documents may be required depending on the loan product.
6. How much business loan can I get in Gwalior?
The loan amount depends on business turnover, profitability, cash flow, credit history, existing liabilities, collateral value where applicable and the lender's policies. There is no fixed loan amount applicable to every business.
Conclusion: Find the Right Business Financing Option in Gwalior
Business financing can help entrepreneurs establish, operate and expand their businesses. Whether you need working capital, machinery financing, infrastructure funding or financial support for expansion, selecting the right loan structure is essential.
If you are looking for a business loan in Gwalior, start by evaluating your funding requirement, organising your financial documents and comparing suitable lending options.
A well-prepared application, realistic funding expectations and a clear repayment strategy can make the financing process more effective.
Looking for business funding in Gwalior? Explore suitable financing options with a bank or authorised financial institution and choose a solution aligned with your business requirements.
Disclaimer: This article is for educational and informational purposes only. Loan eligibility, interest rates, processing fees, repayment terms and approval are determined by the respective lending institution. Government scheme benefits are subject to applicable guidelines and eligibility conditions.
Author Information
Author: Financial Content Team – Chopra MSME Loan Hub
Organization: Chopra MSME Loan Hub, Gwalior, Madhya Pradesh
Expertise: Business Loans, MSME Financing, Corporate Funding, Working Capital, Industrial Finance, Government Loan Schemes and Business Expansion Funding.
Expert Review: Financial Research & Advisory Team – Chopra MSME Loan Hub
Review Focus: Business Loan Eligibility, MSME Financing Options, Loan Documentation, Financial Planning and Indian Banking Guidelines.
Last Updated: November 2026
About Chopra MSME Loan Hub: Chopra MSME Loan Hub provides business financing guidance and assistance to entrepreneurs, manufacturers, MSMEs and established businesses seeking suitable funding solutions for business growth and expansion.